


The topic of inflation or rather deflation has been much spoken about in the past few months and has been the major pain point for Central Banks across the world. While depressed oil prices has been a common factor for declining prices in most advanced economies, the Euro zone in particular is showing anaemic demand and the threat of deflation looms large. The trend among emerging economies is mixed with China showing positive indications of a slowdown whereas in oil importing countries like India the dampened prices are yet to be passed on to the consumers.
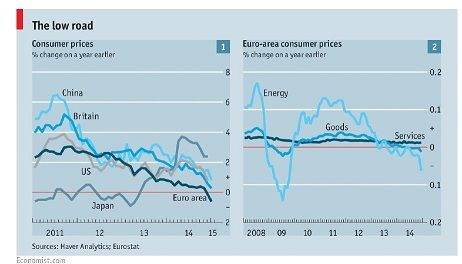
While to the consumer, deflation might yield short term gains with greater purchasing power in the longer horizon, persistent deflation leads a vicious cycle of postponing expenditure and triggering economies into contractions as was the case with Japan.
In the context of the heavily indebted Euro zone economies (read Greece, Portugal, Spain), deflationary tendencies along with sluggish recovery increases the difficulty in repaying nominal debt and thus conflicting with growth stimulating expenditures and initiatives.
The bond markets in the US and Euro have also been reacting to these deflationary signals with fluctuations and volatility. While uncertainty in the Euro and lower long term inflation expectations are pushing down long term bond yields in the US, bond yields in the Euro zone are hovering in the negative reflecting that market participants are hedging strongly against political uncertainty and a very strong possibility of deflation.
While the US continues to be the shining beacon among advanced economies with robust GDP growth and employment gains, wage inflation remains tepid and inflation tendencies remains below the 2% threshold. Despite a strong growth trajectory total inflation was a meagre 0.75% for the 12 months in 2014 and core inflation was around 1.5%. While the core inflation moved up by 1% for the three months ending in December 2014 total inflation number actually showed a decline of 2.5%. These numbers are likely to extend the period of ‘patient ‘outlook by the FED before the imminent rate hike.
As far as the growth starved Euro zone is concerned the key channel towards stimulating the economy and employment (and hopefully inflation) will be stronger exports supported by a depreciating Euro. As far as the US is concerned the FED has its watchful eyes on wage inflation numbers as market participants place a greater probability for a rate hike in the second half of the year.
So what are your thoughts and predictions?
The content for the blog has been sourced using:
Minutes of the Federal Open Market Committee , The high cost of falling prices






Temporibus suscipit et soluta quidem. Ut assumenda facilis eveniet totam soluta ducimus eum. Non voluptatem ipsa reprehenderit eius similique quia numquam.
Enim perferendis omnis modi. Fuga asperiores cupiditate molestiae consequatur. Molestiae eum maiores repellat corporis est accusamus at. Et et exercitationem et est aut. Vel illo est sunt voluptatum magni rem deserunt.
Commodi quo consequatur qui quasi et vero minus distinctio. Quos cupiditate voluptatibus ut molestiae.
See All Comments - 100% Free
WSO depends on everyone being able to pitch in when they know something. Unlock with your email and get bonus: 6 financial modeling lessons free ($199 value)
or Unlock with your social account...