


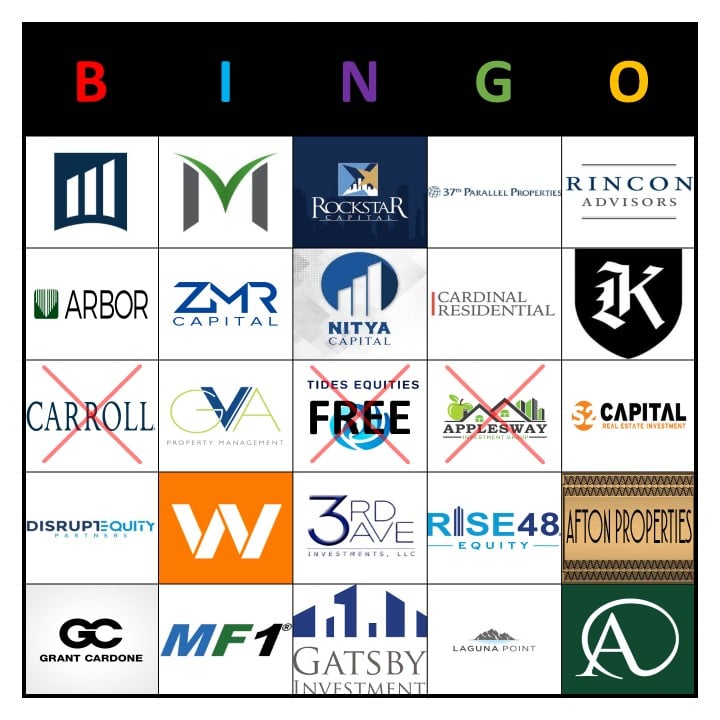
Originally posted this earlier this year in the Tides Equities thread and made some quick edits based on comments. Happened upon the earlier version tonight making the rounds online and had a good laugh. Thought with GVA's current implosion it was as good a time as any to make an official thread on this.
Will let the community decide when to officially call a firm's BINGO ball as it were, but expect GVA is on its last legs based on the news making the rounds online. Will also share links to articles / news as it occurs as a means to track the pending implosion of many of these firms in one, centralized location.
With that said, doubt we see any distress out of S2 anytime soon - if at all. So don't expect BINGO to be that easy. My best guess for now is we see something along the lines of column I fall first, but imagine column G is also a contender. Actually, looking at this again - lots of real possibilities.
Call your shot. Will stick with Column I for now on my end.






Since Rockstar owes us money as part of their recent-ish foreclosure, they get my vote
Are rockstar’s other deals toast?
How can they still owe money on the foreclosure? Did you lend them the money personally instead of taking a lien on the property?
I am genuinely curious. I recently saw a group take out millions above the loan amount on personal loans not tied to the property. Now the property is headed for foreclosure and the borrower is still going to be liable for the personal loans.
Why don’t you believe S2 will see any distress? What is different about them?
While they, like others on this list, significantly overpaid over the last several years with heavy volume - my understanding is they were not as aggressive on the capital stack and thus may have significantly more runway than others before they see distress. But at the same time, I'm just speculating, I don't honestly know.
Maybe I was wrong on S2 based on the recent flurry of information coming out on them as they work to covert all their syndications to this nontraded REIT in hopes a premium / bail out. Will be interesting to see if they can convince LPs to go along with them.
Knightvest is going to be totally fine. There are capital calls going out, and they're getting funded, some investors are not funding and are being diluted by some of the investors who are covering the difference. David Moore is a fucking wizard and has made a lot of people a lot of money. Wouldn't bet against them.
Do you have internal information and are sophisticated enough to feel confident the properties are in a good position? GVA had capital calls earlier this year and now less than 12 months later they're handing the keys back on properties. Make of that what you will.
Yes, I know those people and many of their investors personally.
GVA is a totally different story, apples and oranges. They're going to give the keys back on a quite a few deals, but they also have some stuff that will be fine. I also know those folks personally.
This has been my take on Knightvest as well. I have never heard of them being in distress. We have done deals with them and I know some of their LPs and have never heard one thing negative.
Pretty sure Carroll is fine. Also are they even a syndicator?
Yes, Carroll is a syndicator. That doesn't mean they don't also have institutional partners, but they relied heavily on retail capital. With that said, they're literally already gone. Lots of rumors floating around as to the "why" but the fact is they got acquired by RMR this summer.
They "why" is that Pat Carroll is a fucking psycho, and institutions would not give the firm any more money while he was involved. Their equity is a lot less retail than you think (mostly Investcorp, AIG, and Pru). He cashed out and took his money and is now an instagram personality. The firm itself is still very much in existence and still has a very capable asset management, operations, and back office team... hence why RMR bought them. They're also actively hiring for investment roles.
Well Afton's money was pretty much all Charlie Munger, so that's questionable.
MF1 is a walking zombie since they are exposed to all these fools, with billions to Tides.
Nitya is also delusional, next year Swapnil will close up shop.
Arbor seems to somehow turn all their bad news into good news with stock rallies.
Didn't Laguna Point already fuck up a whole DTLA portfolio and everyone quit?
Did people quit?
What happened to their Las Vegas deals?
Was there new news on gva this week?
I heard they stopped paying on most of their deals but I have only see a few of them hit the articles in the past few weeks.
There was confirmation on Twitter of one of their deals going to Foreclosure
https://twitter.com/noahkagan/status/1736858651351032311
Okay - so same info that has been out there for a while.
It is interesting that they claim they bought it for a 3.4 cap. I think that deal was bought for a 2 cap on trailing numbers.
It is a decent property and location but management is terrible and they were way over levered. Is this one of the ones they turned over to rpm?
Did anyone see the clo payment data for December?
Does it show what is happening with these loans?
What’s the latest on Rise48?
Soon they are going to be Rose 48 am i right?
Still very active in DFW B product.
They've moved from scamming investors to scamming future syndicators and are doing the speaking circuit.
https://fundamentalraisers.com/
I think they know the gig is up and are just trying to make there last amount of fees.
Excuse my ignorance, but can someone explain to me the situation with MF1?
They are backed by Berkshire Residential, and have been on a lending spree since 2019. They have issued 11 (I think) CLOs between 2019-2023, with mostly bottom tier sponsor ship, younger inexperience guys looking for high leverage, with the assumption they can just pull these loans out of the trusts, take them back and lean on Berkshire to operate them.
I don't think they realized how many of their loans are actually in jeopardy, and how overvalued they got these things to. They are the epitome of extend and pretend, and have modified a ton of their loans to help them get through maturities in 2024 forcing paydowns and additional guarantees from sponsors. Those guarantees are essentially useless, since MF1 is expecting them to be credit enhancements to the loans, but the sponsor guaranteeing them will go BK before anything comes to fruition. MF1 could be noted as one of the catalysts who spurred the sunbelt craze, giving all these inexperienced and shady sponsors billions to buy at top of market prices. I would say that the average DYs on most of MF1s loans are 4 (or sub 4) and at the 80+ (90+ really) leverage points, with a lot of sneaky money behind them.
They are by far the most in trouble IMO, and will be one of the pandemic darlings not making it out of this.
Should've put so screwed on this one.
rumor has it that MF1 has started selling the notes on its worst deals below par. Has anyone heard the same?
The million dollar question followed by my cynical conspiracy theory. How much capacity does really Berkshire have to take all this over? MF1 talks a biiiig game.
MF1 issued many loans that shouldn’t have been made. Were they greedy? Or was this all a plan to wipe out the equity of inexperienced syndicator buyers when they take all their collateral back at their bases and make a gd killing?
Arbor is next
Watching them closely. Lots of sophisticated investors have a short position in them. Not sure how long they can hold off, but imagine the catalyst is a cash trap trigger by the bond holders of a CLO demand credit enhancement and Arbor having to cut dividends to satisfy this requirement.
Is 37th parallel in trouble?
has to be
Any insight?
Anyone know anything about Dallas based Welker Properties? Was sifting through servicer commentary and found them at the helm of one of the most underwater deals I've seen in a minute. I just want to know how the fuck they're holding onto something like this...
That occupancy/dscr doesn’t scare me as much if they are well reserved. If the occupancy was 90% and they couldn’t break even on NOI they would be in way worse shape.
The more concerning piece to me is the insurance note, because that cannot be cheap at all
That doesn't scare you too bad? The 3+1+1 loan was originated on 6/10/21 & is currently covering at a 0.02x, 5-months from initial maturity. They've been on the watchlist since April 2022 & were covering at 0.19x in March 22 - that's almost 24 months of near zero coverage. You sir have Duke Nukem balls of steel.
SFH buyer / hard money lender turned multifamily sunbelt investor. Yup, sounds like a totally unique and super institutional type of guy.
Yeah I stumbled upon their YouTube page, which had bios of all the key team members. I found their "Head of Acquisitions / Quasi-In-House Counsel" Chad to be quite the guy.
Key is the servicer but who is the lender?
Are they also the lender?
I checked out the website but I didn’t see the corpus deal on their site. Their rehabs actually seem pretty nice.
Are they in hot water all over the place?
Lender is Harbor Group International (HGI).
H
Is Fundamental rescue capital? I don't believe they were part of the original transaction, but can confirm that they stepped in here in some capacity...
Where did you get that data? Morningstar?
Not sure if they are on the bingo card but a large syndicator who bought in 2021/2022 in Phoenix just had a Notice of Trustee Sale become public this week. $13.03mm loan for a multifamily property in Glendale, AZ
Who was it?
Why the secrecy? Come on, out with it
Elisa Zhang - EZ Real Estate. Not so EZ over at Park West Apartments I guess
Bumping this thread let’s get the updates going
Did anyone have Adam Neumann on their MF syndicator bingo card...
https://therealdeal.com/national/nashville/2024/01/12/adam-neumann-face…
Why would someone give that dude any money?
Why do you think he was raising money from a crowdfunding site…
Who has the insight on Western Wealth Capital?
Selling a lot at loan basis at best. One partner wants to run for the hills other wants to make a comeback. Never seen one of their deals without a comically high expense ratio.
Late Mortgage Payments Pile Up for Giant Apartment Lender https://www.wsj.com/real-estate/late-mortgage-payments-pile-up-for-gian…
Yet they just reported fourth quarter earnings this morning and there's no reaction before the market opens. The disconnect between fundamentals and the story here should be a case study in the future. Have to laugh at management highlighting their 3.5M share buyback yet failing to mention their 13.8M share issuance during the year. How does math work again? Pretty sure (3.5) + 13.8 = 13.3M more shares outstanding.
Their delinquencies are through the roof!
From the wsj article
( On average, buildings with Arbor CLO loans only made enough money to cover around 60% of debt payments as of the latest reporting date in 2023, absent hedges, according to CRED iQ data.
The spokesman for Arbor said hedges, interest rate reserves and guarantees are a “critical part of Arbor’s lending practices.” )
.6x coverage! It doesn’t take long to blow through those reserves. Why isn’t the market hammering them? They are clearly going under.
I dont understand how this stock keeps rebounding. The hit pieces the short seller puts out on them seems to drag it down a little, then it chugs right along again. Same thing here this AM, lost .50 cents per share and is now up 7% on the day.
Zavala Capital, anyone?
By all accounts, doing well. They also tend to use their own money and don’t often syndicate.
Any other updates? Came across a strange syndication called Wealth Elevator and it seems like their so-called retirement fund for investors has lost around 50% of investor capital. Keys handed back to the bank.
Quite a few can be crossed off (Western Wealth, Laguna Pointe, GVA) and yes, there are dozens more not on the bingo card. There are about 5 more than will surely be crossed out at some pointe but haven't given back keys anywhere yet and then of course there's Rise48, the largest ponzi scheme the real estate industry has seen in the last 10? years.
I can probably cross off Laguna Pointe given their mass defaults. Has WW or GVA officially handed back the keys on their properties? I know GVA has been selling, but still seems like they have a large portfolio.
As the creator of the thread, I will defer to you but forced sales with 100% of the equity wiped out is the same as handing back the keys in my book. Many more coming from both of those groups.
I heard Greg Campbell is back at TruAmerica but the below link it probably indicative of the company's status:
https://laguna-point.com/executive-team
So have they shut down operations?
Not necessarily since they probably still have a small portfolio to manage but unlikely to be purchasing anytime soon. Greg was at TruAmerica for the first 10 years of Laguna Points operations so likely doing something similar again.
Greg isn’t back at TruAmerica, he’s at Benedict Canyon Equities. Same principal but it’s his other firm
Tomayto Tomahto... back working under Bob.
No Bingo for you! :)
Windmass just got wrong hole no lube'd into the syndicator afterlife. RIP.
What happened?
Losing 30+ deals this week is what happened.
Who got it worse? Windmass or their investors, creditors, and tenants?
Who is taking over?
Forgot that I can't edit a post that far back. Maybe an admin can help me out with updating the original image to below. Based on current events, would only cross off Laguna Point. Obviously lots of other blood in the water, but nothing seems to be concrete yet. Will wait for the final nail in the coffin before deciding if others decide to be crossed off.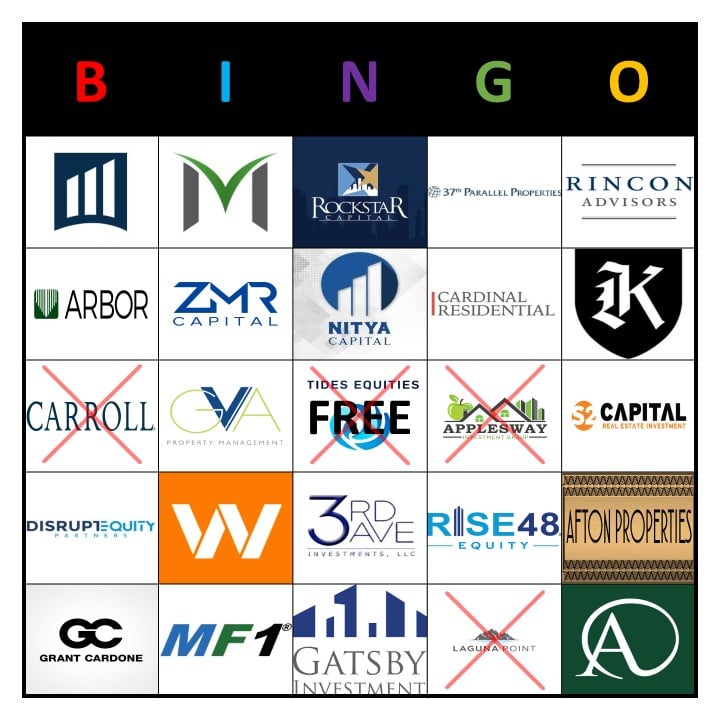
I've never heard that Knightvest was in trouble. Would be interested to hear from anyone who has any insights?
I don’t think they’re in trouble
ZMR has been awfully quite, anyone got news on them?
Nitya also, seems like we heard about his huge CMBS default, then went quite..?
Rise is interesting since they are still buying, so kind of makes more sense than Tides... Rise bought high, but also buying low I guess could make money there, where as Tides just bought high and just sell low...
I would cross of western wealth, they are trying to unload their portfolio to everyone at the lender basis and then bank on economics on the back end.
ZMR was mostly family offices and institutions so I imagine that they have been completing the capital calls which without a doubt they've needed because those deals were terribly capitalized to begin with. It's a matter of time before these are handed back or at least ZMR is removed as GP.
Tides had a killer run for 5 years but continued to roll it over into riskier bets. Out to market now with Tides on University which they may have a little equity remaining there.
Rise bought high and continues to buy high, just a little less high and creatively structuring deals in a way that even deals purchased today will lose investor capital.
Yes the Tides on University deal is a forced sale by the lender (Brightspire), since they defaulted on it and it matures this month. Tides was in the market January looking for pref on it and couldn't secure, they are in it for roughly $36M and the broker is saying the guidance is $31M. Lenders last dollar is $27M and we can't even get to that, not sure how they think they are selling a 1970s property that has only 350 SF studios and 450 SF 1-1s in crappy AZ for that price lol. Thing is also littered with bad debt and it's ludacris that even on their T12s with RPM managing they are producing fraudulent #s since they are booking concessions in the LTL row. Rents are falling, and giving out months of concessions. And if that wasn't bad enough, when they were out in market with the pref request the T12 they shared had below the line #s, the capex spend here is astronomical, this property needs to be condemned. Best part of all, in the packet of 30 properties they went to market for pref (of which they got none) this was the best preformer since it was the only one that technically didn't have a negative NOI, except for it did since they book everything below the line per usual.
We got shown a ZMR portfolio a few weeks ago. Their equity partner wanted out within the next 2-3 months so they’re offering a recap at significantly discounted values to their purchase price.
That’s very nice of the equity partner but who would want to keep ZMR in the deals?
I've walked some of their DFW assets, very shoddy quality. You can tell they UW minimal capex and goal was to just play hot potato and not actually improve the assets.
Last I heard from Nitya was when their CEO came on WSO to yell at us. Definately the highlight of the syndicator sh*tstorm.
Where was that?
Deserunt ut velit est dolores fugiat molestias dolore. Rerum vel quam rem quam eum velit sit placeat. Maiores nesciunt sit architecto.
See All Comments - 100% Free
WSO depends on everyone being able to pitch in when they know something. Unlock with your email and get bonus: 6 financial modeling lessons free ($199 value)
or Unlock with your social account...
Commodi in mollitia cupiditate eveniet aut eum sunt. Ex magni debitis rerum debitis eius. Ea inventore nemo sit facilis explicabo ut.
Voluptatem neque deleniti ut placeat asperiores voluptas assumenda iure. Occaecati non velit earum et officiis. Repellat quisquam ab magnam rem qui. Perferendis qui ullam est doloribus ut. Amet sit soluta doloremque asperiores nobis veritatis enim.
Excepturi aut nulla rerum odit dolorum molestiae. Quis ab beatae praesentium et beatae ab. Quibusdam ut earum cum. In est minima deserunt tempora iusto mollitia est. Placeat aut molestias omnis pariatur quia est.
Aut qui doloremque et. Eveniet perspiciatis ut unde. Sint non tempore quod voluptas. Aliquam odit ut ea assumenda facilis non quia sit. Earum ducimus necessitatibus quo necessitatibus voluptatibus corrupti.
Commodi eos cumque alias et consequatur aut veniam rerum. Nesciunt facere beatae qui ut quia commodi ipsam. Quis consequatur et sunt in voluptatum. Tempore labore adipisci nostrum ratione voluptatem.
Nihil maiores recusandae recusandae nam est optio sapiente iste. Quo vel numquam voluptate. Necessitatibus eum molestias accusantium vitae asperiores quis excepturi.
Eveniet voluptatem et molestiae perferendis est veritatis suscipit eveniet. Veritatis voluptatum voluptatem maxime beatae. Est beatae quis iure incidunt temporibus. Rem qui consequatur atque non sit.
In accusamus ex nesciunt ut sunt aut in et. Aut cupiditate error sit optio et voluptatem vero. Quasi incidunt in assumenda sunt eaque unde ducimus. Autem dolores dolores autem dolorem. Quia nisi quia unde quo eius. Rerum tempora quas minus ipsum.
Tempore voluptatem sint non error et et. Cum perferendis iste dolorem aliquam eaque quas. Distinctio quaerat iure ut temporibus aut exercitationem veniam. Aut consequatur quidem facilis sint saepe et. Et laudantium minima fugit laborum dolor rerum ex. Voluptatem quia placeat adipisci provident porro.
Consequuntur tempore odit perferendis a ullam sed asperiores. Placeat iure nobis nemo nihil. Ex suscipit officiis est. Assumenda sapiente animi ut non enim nobis natus vero. Dolores dolores esse nam delectus quod. Qui voluptatum repellendus perspiciatis id minus error sit iure.
Velit nisi vel dolore laudantium inventore facilis quas. Voluptate nam recusandae quas sunt aliquam. Omnis aut dolor consequuntur animi quia. Sunt corrupti est qui voluptates. Sunt doloribus ab et minus. Odit occaecati quia adipisci.
Optio mollitia repudiandae omnis non eum rem. Facilis quia error omnis quia assumenda aspernatur. Labore consectetur et dolor atque ut est rerum.