
Calendar Spreads - Need help

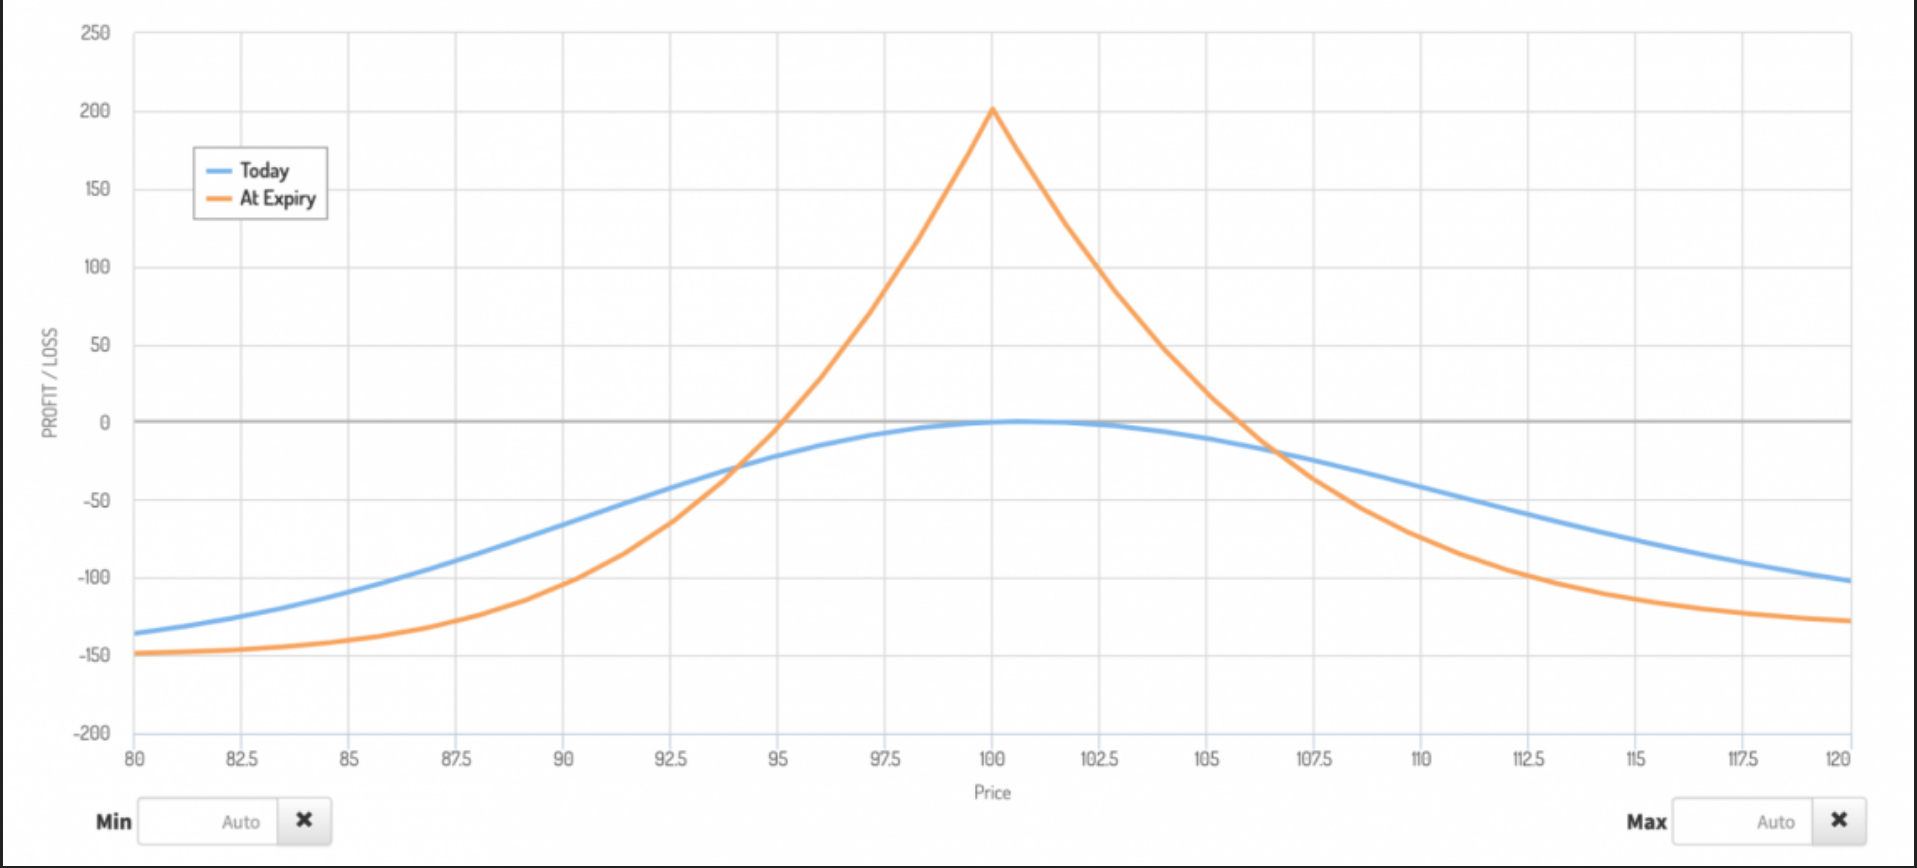
For both Long Call / Put, I understand the logic of how to profit; namely, one hopes for the strike price to stay either below (in case of call) or above (for put) to get the premium from the first leg as it expires worthless. Then, one has the hope that it will either rise in value (long call) or decline (long put) to maximize profit in the second leg. I am confused, however, by this graph. Why is it that the price remaining as close to the strike price maximizes the profit of a calendar spread? Numerical examples would be especially helpful.






Aut enim fuga natus aut rerum laudantium. Voluptatem vero et officia et nam ea qui non.
Accusamus nulla nostrum deserunt sunt sint adipisci. Id dicta ut neque tempora error. Commodi dolorum eius voluptatem eius saepe sint minima amet.
Dignissimos voluptatem omnis et alias voluptatum rerum amet. Accusantium voluptatem dicta iure porro iure. Corporis quas ducimus architecto quis rerum. Nobis dolores et recusandae quia commodi fugit neque quasi.
See All Comments - 100% Free
WSO depends on everyone being able to pitch in when they know something. Unlock with your email and get bonus: 6 financial modeling lessons free ($199 value)
or Unlock with your social account...