
Accounting Depreciation vs Tax Depreciation
Accounting depreciation is used for financial reporting, while Tax depreciation reduces tax bills.

Accounting depreciation is the allocation of the cost of an asset over the period that it is in use. Tax depreciation is a completely different proposition in that it is governed by the rigid timeframes prescribed by the tax code (primarily the MACRS rules). In the US, the tax depreciation method is MACRS. Other countries have their own capital allowance regimes, but the book-to-tax split is the same.
Both systems recover the asset's cost over its life, but on very different schedules. Those timing differences in schedules usually create deferred tax liabilities on the balance sheet.
Imagine you buy a piece of plant and equipment for $1m. Under GAAP, you can't write that full cost off immediately. You have to depreciate it over its useful economic life. The tax code, on the other hand, will often allow you to write off the full amount immediately. So you're immediately in a situation where the accounting cost is very different from the tax cost.
Here's the twist. The same machine produces two different depreciation figures, one for the books and one for the tax return. That's not an error; that's intentional. Accounting depreciation is for the investors; tax depreciation is for the IRS. Two different rule books, two different statements, and they rarely, if ever, come up with the same figure for the year.
What Is Accounting Depreciation?
Accounting depreciation (or book depreciation) is the systematic allocation of a fixed asset's cost, less its estimated salvage value, over its useful economic life. In most cases, it is stated on the income statement as an expense, in COGS or operating expenses depending on how the asset is used. For manufacturers, depreciation on production equipment is first capitalized into inventory and only hits the income statement through COGS when the goods are sold.
This is for matching purposes. The truck costing $60k with a $10k salvage value and a 5-year useful life would produce 10K of depreciation ((60k − $10k) ÷ 5). If you expensed the full $60k in year one, that would wipe out year one earnings and inflate all the subsequent years.
Here, depreciation is calculated using the most common depreciation technique, the Straight-Line Method, which is as follows:
Annual straight-line depreciation = (Cost − Salvage Value) ÷ Useful Life
Companies reporting under US GAAP or IFRS have significant flexibility in how they depreciate assets. Management chooses 3 key things: the method, the useful life estimate, and the salvage value. Those choices aim to reflect the asset's actual pattern of economic use.
That flexibility has its limits. The estimates have to be supported and are subject to auditor review. IFRS requires management to review the method, useful life, and residual value at least annually. When an estimate changes, the impact is applied going forward rather than restated.
A quick distinction: depreciation is for tangible assets (buildings, equipment, etc.). Land is the one exception. Land doesn't wear out, so it's not depreciated at all. Land improvements (paving, fencing, etc.) are depreciated.
Amortization is the same idea for finite-lived intangibles such as patents and purchased software. Intangibles with indefinite lives, including goodwill, aren't amortized by public companies at all. They're tested for impairment instead.
Carrying value matters more than original cost for a very important reason. A machine bought for $500,000, with $300,000 of accumulated depreciation, has a $200,000 book value, which is what shows up on the balance sheet. Sell it for more than $200,000, and you book a gain. Sell it for less, and you take a loss. Investors price the carrying value, not the historical purchase price.
- Accounting depreciation and tax depreciation are two separate systems that run in parallel. Accounting depreciation is the one that follows GAAP and is the one that reports the profit to the investors. Tax depreciation is the one that follows IRS rules and is the one that's used to calculate your taxable income on your tax return.
- Both methods end up with the same total cost over the life of the asset. It's just the timing that's different. Under MACRS, the tax depreciation will front-load the deductions, whereas the book depreciation is generally straight-line and therefore evenly spread.
- That cumulative timing gap gives rise to a deferred tax liability (DTL) on the balance sheet, which is one of the most heavily tested and commonly modeled items in finance.
- IFRS deals with depreciation in a different way than US GAAP (it allows component depreciation and periodic asset revaluation, which US GAAP does not).
- The clean way to do it in valuation is to forecast cash taxes (which are driven by tax depreciation) rather than book taxes, as book taxes are not actually leaving the business. A lot of models will start with a book effective rate and then adjust for the deferred taxes separately.
Common Accounting Depreciation Methods
Under both US GAAP and IFRS, management picks the depreciation method that best reflects how the asset gets used up. The method menu is the same; the differences between the two regimes show up elsewhere, as we'll cover below.
The choice should match the asset's economic pattern, though earnings smoothness also influences it in practice. So let’s take a look at some of the types below:
- Straight-line: Equal expense each year. (Cost minus salvage) divided by useful life. See our straight-line depreciation page for the full mechanics
- Double-declining balance: An accelerated method that front-loads expense. The annual charge is twice the straight-line rate applied to the asset's beginning book value, so a five-year asset depreciates at 40% a year.
- Units of production: Ties depreciation to actual output. Common for manufacturing equipment or natural resource assets
- Sum-of-the-years' digits: Another accelerated method, less common in practice.
Different industries gravitate toward different methods for legitimate reasons. For example:
- Real estate and infrastructure use straight-line depreciation as the economic benefit is pretty much even over the decades.
- Straight-line depreciation over lives that have been getting longer. All the big boys (Alphabet, Microsoft, Amazon, and Meta) have extended their server useful lives in the 2020s, and with their hundreds of billions in equipment, the impact of a small change in the life is going to be massive in terms of earnings. Alphabet's extension in 2023 reduced its depreciation expense by $3.9bn and increased its net income by $3.0bn or $0.24 per diluted share. That's the flexibility we referred to earlier, in real terms.
- Manufacturers with metered equipment lean on units of production
- Mining, oil and gas use depletion methods which are essentially units of production but track the extraction of the resource rather than the hours of machine operation.
The vast majority of US companies will still go with straight-line for their financial reporting as it produces the smoothest earnings. Smooth earnings are what investors are pricing on and to switch to an accelerated method generally requires both a sound reason and disclosure of the change.
Depreciation Under IFRS vs. US GAAP
Everything so far applies under both frameworks. IFRS then layers on a few requirements US GAAP doesn't have, and if you're reading a foreign issuer's annual report, these are the ones that will change what you see:
Component Depreciation
Under IAS 16 (IFRS), you're required to depreciate any significant component of an asset with a different useful life separately. If you buy a commercial aircraft, you don't just depreciate 'the plane'.
You split the engines, the airframe, and the interior fit-out and depreciate each on its own schedule. US GAAP allows this but doesn't require it, so most US filers don't do it. The IFRS approach results in a more accurate expense pattern at the expense of more accounting.
Revaluation Model
IFRS allows a company to carry its PP&E at fair value rather than historical cost. There are two constraints that prevent it from being a free lever. Revaluations have to be frequent enough to ensure that the carrying amount doesn't drift materially from fair value, and the election is on a class of assets basis, so you can't revalue just the assets that have appreciated. The increases go to OCI and accumulate in a revaluation surplus in equity.
Decreases go to profit or loss (apart from the situation where they reverse a surplus previously recognized on that asset). Depreciation thereafter runs down on the new carrying amount. US GAAP provides no equivalent. An asset at historical cost less accumulated depreciation remains at that amount unless it is impaired.
The frameworks also part company on reversals. If an impaired asset does recover under IFRS, the write-down can be reversed (apart from goodwill). US GAAP has no such facility, and a US asset written down remains written down.
Useful Life Review
IFRS requires a review of useful life, residual value, and depreciation method each year. US GAAP puts no cadence on it and simply requires that the estimates be reviewed when circumstances change. The IFRS requirement for an annual review means that IFRS filers have a built-in trigger to go back and reassess these estimates. US filers only do so when they are prompted to.
Under both frameworks, a revision is treated as a change in accounting estimate and is applied going forward. The prior years are not restated. The carrying amount is simply spread over the revised remaining life, which is why a life extension will immediately result in lower depreciation expense.
Tax Depreciation
There is no international version of MACRS. Each country writes its own rules. The UK has its capital allowances, Germany has its AfA schedules, etc. The size of the book tax gap will vary from country to country.
The US maintains the two systems as completely independent of each other, whereas in a number of the continental European jurisdictions there has historically been a much closer linkage between the tax accounts and the statutory accounts. Germany's approach is the classic example (though that has in fact relaxed over time). The tighter the conformity, the smaller the deferred tax balances.
What Is Tax Depreciation?
Tax depreciation is the deduction the IRS allows you to take against taxable income for the wear and tear on business assets. It follows the Internal Revenue Code, not GAAP, and the rules leave almost no room for management judgment.
The system most US businesses use is MACRS, the Modified Accelerated Cost Recovery System. MACRS assigns every asset to a class with a fixed recovery period and a prescribed depreciation method.
- A computer is 5-year property.
- Office furniture is 7-year property.
- Nonresidential real property is 39-year property, and
- residential rental property is 27.5-year property.
The 'year' refers to the recovery period, not the asset's age.
Note
See our MACRS page for the full asset class table.
Beyond standard MACRS, two provisions can dramatically accelerate tax deductions in the year an asset is placed in service:
- Section 179 allows small and mid-sized businesses to immediately expense the full cost of qualifying assets. The 2026 cap is $2.56m with a dollar-for-dollar phase-out once total qualifying purchases exceed $4.09m. Two caps apply (not one). Beyond the dollar cap, the deduction cannot exceed the business's taxable income, so Section 179 can never result in a loss. Any excess can be carried forward.
- The order is important. Section 179 first, then bonus depreciation, and then MACRS on the remainder. Many states also decouple from the federal bonus depreciation rules, so the state deduction can end up being quite different from the federal deduction.
- Bonus depreciation: permits an extra first-year deduction on qualifying property. The Tax Cuts and Jobs Act of 2017 initiated a phase-down (80% in 2023, 60% in 2024, 40% in early 2025). The One Big Beautiful Bill Act (signed July 2025) has reversed that. For property acquired and placed in service after January 19, 2025, 100% bonus depreciation is back and is permanent.
- The acquisition date is what matters. Property that is under a binding contract prior to 20th January 2025 remains on the old phase-down schedule even if it goes into service afterward.
The policy rationale is straightforward, really. Faster deductions lead to lower current tax liability, more cash to reinvest, and a greater incentive to spend on capital. Tax depreciation is as much an economic policy tool as it is an accounting exercise.
Accounting Depreciation vs. Tax Depreciation
Both methods spread an asset's cost over time, but that's where the similarities end. The two systems answer different questions for different audiences.
Let’s see the differences in the table below:
| Feature | Accounting depreciation | Tax depreciation |
|---|---|---|
| Purpose | Match expense to economic benefit for investors and lenders | Calculate taxable income for the IRS |
| Governing rules | US GAAP or IFRS | Internal Revenue Code (MACRS) |
| Method choice | Management discretion based on use pattern | Prescribed by tax law |
| Useful life | Estimated by management | Fixed by asset class |
| Salvage value | Estimated and subtracted from the depreciable base | Assumed to be zero under MACRS |
| Pattern | Usually straight-line, smooth | Accelerated, front-loaded |
| Where it appears | Income statement and 10-K filings | Tax return only |
Tax depreciation is generally faster than accounting depreciation in the early years of an asset's life. The difference is most marked in equipment. Real property is the principal exception, as MACRS requires straight-line depreciation over 39 years, and assets on ADS can in fact depreciate more slowly than on the books.
The total cost over the life of the asset is the same under either system. You can't depreciate more than the cost of the asset. The difference is when that deduction occurs, and the timing of that deduction has real implications for cash flow, reported earnings, and valuation.
That mismatch is by far the biggest single source of deferred tax liabilities on corporate balance sheets (though there are others). Installment sales, unrealized gains, and capitalized software are other sources of the liabilities, and there is a separate set of differences which give rise to deferred tax assets (loss carryforwards and warranty reserves being the main examples). Depreciation is of course by far the biggest and most widespread, as virtually every operating company will have some form of fixed assets.
Accounting Depreciation vs. Tax Depreciation Example
In this example, a company buys a piece of equipment for $100,000 with no salvage value. For its books, it uses straight-line depreciation over 10 years. For tax purposes, the asset is a 5-year MACRS property (using the standard half-year convention).
Note the zero salvage value. That assumption is why the two columns total the same amount. Give the asset a $10,000 book salvage value, and book depreciation would total $90,000 against $100,000 for tax, because MACRS always writes the asset down to zero.
Here's how the two schedules compare side by side:
| Year | Book Depreciation (SL) | Tax Depreciation (MACRS) | Difference (Tax minus Book) |
|---|---|---|---|
| 1 | $10,000 | $20,000 | $10,000 |
| 2 | $10,000 | $32,000 | $22,000 |
| 3 | $10,000 | $19,200 | $9,200 |
| 4 | $10,000 | $11,520 | $1,520 |
| 5 | $10,000 | $11,520 | $1,520 |
| 6 | $10,000 | $5,760 | ($4,240) |
| 7 | $10,000 | $0 | ($10,000) |
| 8 | $10,000 | $0 | ($10,000) |
| 9 | $10,000 | $0 | ($10,000) |
| 10 | $10,000 | $0 | ($10,000) |
| Total | $100,000 | $100,000 | $0 |
[Note: This example uses the standard MACRS schedule to show the timing mechanics as clearly as possible. In practice, under current law, the company could elect 100% bonus depreciation and deduct the full $100,000 in year one. That doesn't change the principle. It makes the gap larger and the deferred tax liability bigger.]
Notice the lifetime totals: $100,000 either way. What's wildly different is the timing.
In years 1 to 5, tax depreciation is greater than book depreciation. That results in lower taxable income and hence lower cash taxes paid, which is a genuine but temporary improvement in cash flow. The tax code isn't being kind in any way. It's simply allowing the company to defer the tax, not avoid it.
By year 6, the pattern is reversed. Book depreciation continues at $10k a year while tax depreciation is all but used up. Book expense now exceeds tax expense, taxable income exceeds book income, and the company is now paying down the deferral. Accountants refer to this as a reversal, which is why the difference is termed temporary rather than permanent.
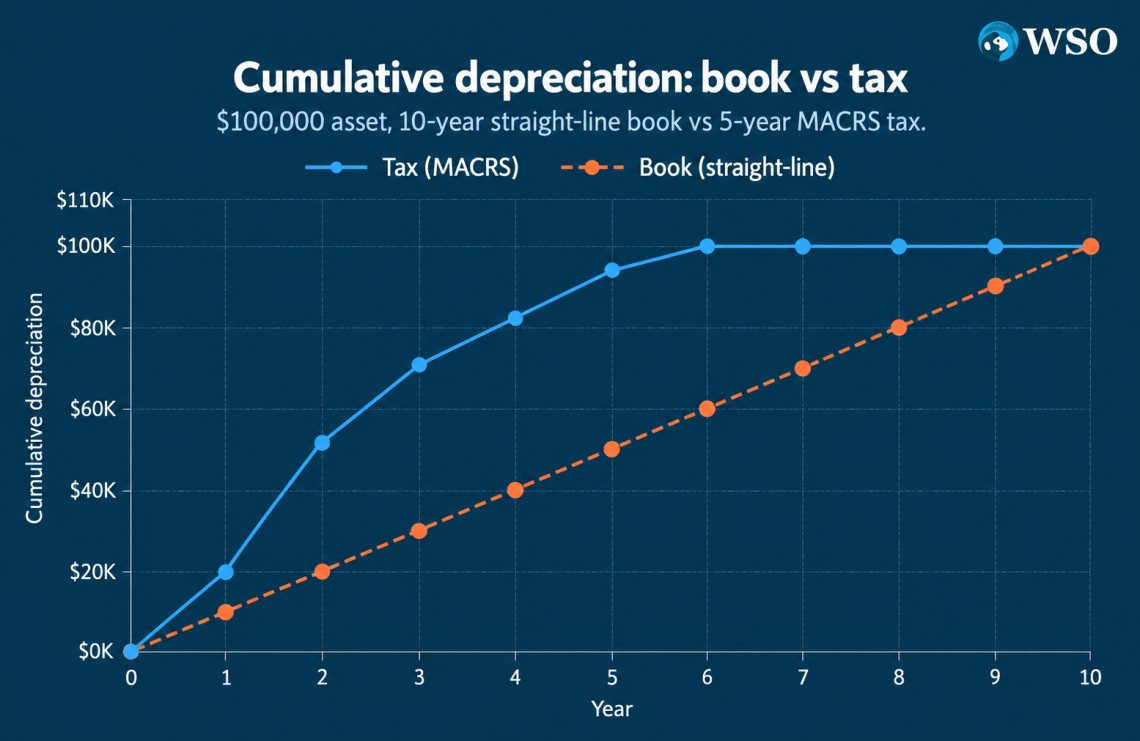
(Image: MACRS vs straight-line depreciation schedule over 10 years, showing cumulative book and tax depreciation)
What Are Deferred Tax Liabilities?
That accumulated timing gap isn't just sitting there. It creates a real balance sheet liability in the form of a deferred tax liability (DTL).
DTL = cumulative temporary difference × the enacted tax rate expected to apply when it reverses.
Temporary differences will eventually reverse. Depreciation is the classic example: the deduction is larger now and smaller later, but the total is the same, so the difference will reverse in the future. Only temporary differences give rise to deferred taxes.
Permanent differences never reverse. Municipal bond interest is tax-exempt but is included in book income. Fines and penalties are expensed but are not deductible.
Percentage depletion can exceed the cost of the asset. These affect the effective tax rate but give rise to no deferred tax balance as there is nothing to reverse.
By the end of year 5 in our example, the company has expensed $94,240 for tax purposes and only $50,000 on the books. That's a $44,240 difference. Multiply that by the 21% federal corporate tax rate, and you get a DTL of about $9,290. The company hasn't underpaid tax at all. It's just paid less now in return for paying more later.
[We're using the 21% federal rate for simplicity. In reality, companies use a blended federal/state rate, and the measurement rule is the enacted rate that's expected to be in place when the difference reverses. That's not theoretical at all. When the corporate rate went from 35% to 21% in 2017, companies had to re-measure their entire deferred tax balances, which resulted in huge one-off swings in earnings that were completely unrelated to operating performance.]
Open up any large industrial company's 10-K on EDGAR and head over to the income tax footnote. There'll be a table of the components of the deferred tax assets and liabilities, and 'property, plant and equipment' or 'depreciation' will be right at the top of the liabilities side of the table, invariably the largest single item.
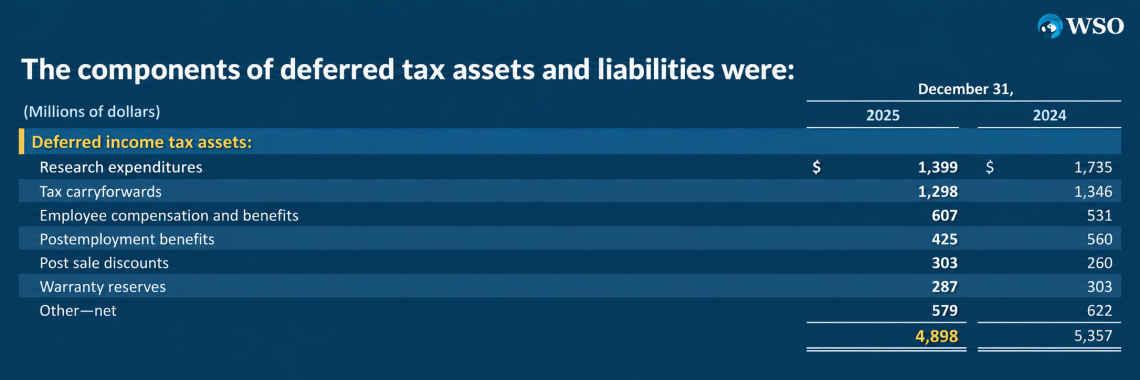
(Source: Caterpillar Inc. 2025 Form 10-K, page 79. Filed with the SEC, February 2026.)
For anyone building a financial model, this matters. Reported tax expense on the income statement is based on book numbers, but cash taxes paid track the tax return.
If you're forecasting free cash flow for a discounted cash flow (DCF) valuation, you want cash taxes, not book taxes. Use book taxes when tax depreciation is running ahead, and you overstate the company's near-term tax bill. That understates early free cash flow, and because early cash flows carry the most weight in a DCF, it understates the valuation.
It's also why mature companies with steady capital spending tend to carry large, persistent DTLs. New assets being depreciated for tax keep refilling the bucket faster than the old ones drain it.
In practice, there are two ways to handle it. Build a separate tax depreciation schedule and compute cash taxes directly, or start from book tax expense and add back the change in deferred taxes as a non-cash adjustment. The second is faster and more common; the first is more accurate when capital spending is large.
Depreciation vs. Impairment
Depreciation is predictable. You pick a useful life, you pick a method, and the asset then gives up a set amount of value each year until it reaches its salvage value.
Impairment is the one that jumps you. The carrying value has drifted above what the asset is actually worth, and at some point you have to stop pretending.
The two regimes sniff it out differently.
Under US GAAP (ASC 360), impairment testing is not routine. It's only carried out when there are events which indicate that the carrying amount of the asset may not be recoverable. These could be a significant drop in market value, a change in the use of the asset, or a history of operating losses. The test is also performed at the asset group level (i.e., the smallest group of assets that generate largely independent cash flows) rather than asset by asset. When the test is triggered, it involves two steps:
- Recoverability. Compare carrying value to the undiscounted future cash flows the asset group is expected to generate. Undiscounted is the word that trips people up. If carrying value exceeds that total, the asset is impaired.
- Measurement. The loss is carrying value minus fair value, and it hits the income statement.
IFRS under IAS 36 makes use of a single comparison rather than two (carrying amount against recoverable amount, which is the higher of fair value less costs to sell and value in use). Value in use is the present value of the asset's future cash flows. That's the key difference.
GAAP screens against undiscounted cash flows; IFRS screens against discounted cash flows. As discounting results in a lower number, the IFRS threshold is more easily breached. On the same facts, an IFRS filer will frequently recognize an impairment where a US filer would recognize nothing at all, or would recognize it a year or two later. IFRS also tests at the cash generating unit level (the IFRS equivalent of the GAAP asset group).
The real interest is in the reaction gap. If you announce an impairment, investors lose it. The depreciation line right alongside it gets a shrug. Both are non-cash, and both are eating into earnings. One at least has the decency to be on schedule.
Worth knowing for valuation work. An impairment will also create or unwind a deferred tax liability (DTL) as the tax basis won't normally change simply because the asset has been written down by the accountants. The DTL calculation becomes a bit more complicated, but the principle is exactly the same as what we discussed above.
Accounting Depreciation Vs. Tax Depreciation FAQs
Yes, and most US companies do exactly that. The books follow GAAP and usually use straight-line. The tax return follows the Internal Revenue Code and usually runs on MACRS. Nothing requires the two to match. Depreciation has no book-tax conformity requirement, unlike LIFO inventory, where the tax code does force the same method on the financial statements. The two systems are kept apart deliberately, because they're answering different questions.
No, they're quite closely related. Both accelerate the deduction of tax, just in different ways. Section 179 has a dollar limit, and it phases out for larger purchases. Importantly, it cannot create a loss (it can't ever exceed your taxable income).
Bonus depreciation has no dollar limit, no income limit, and can in fact cause a company to go into a net operating loss. It applies automatically unless you elect out by asset class. When both are available, Section 179 is applied first, then bonus, then regular MACRS on the remainder.
Because that's what Congress wants. Accelerated tax depreciation is simply a policy tool to get businesses to invest. The faster the write-off, the lower the tax bill in the year it's claimed, the more cash the business has to put back to work, and the greater the incentive to go out and buy assets.
Depreciation itself is non-cash, so on its own it doesn't move cash. Two things follow, and it's worth keeping those two things separate.
Firstly, depreciation is deducted in the calculation of net income, but of course no actual cash has left the business, so it's added back in the operating section of the cash flow statement. It's a simple reversal of a non-cash charge and would be done regardless of whether or not corporate taxes existed.
Second, tax depreciation genuinely does affect cash, because it reduces taxable income and therefore the cash taxes actually paid. That's called the depreciation tax shield, and it's worth roughly the depreciation amount multiplied by the tax rate. A $100,000 deduction at a 21% rate saves about $21,000 in cash tax.
DTLs sit on the balance sheet as something the company will eventually pay in cash, except nobody knows exactly when. Most analysts split the difference and treat them as part debt, part equity when working out enterprise value. Which way they lean depends on whether the company keeps reinvesting in new assets or lets the liability slowly unwind.
Free Resources
To continue learning and advancing your career, check out these additional helpful WSO resources:


or Want to Sign up with your social account?