
The Comeback of Citi and Rise of EBs

Thoughts?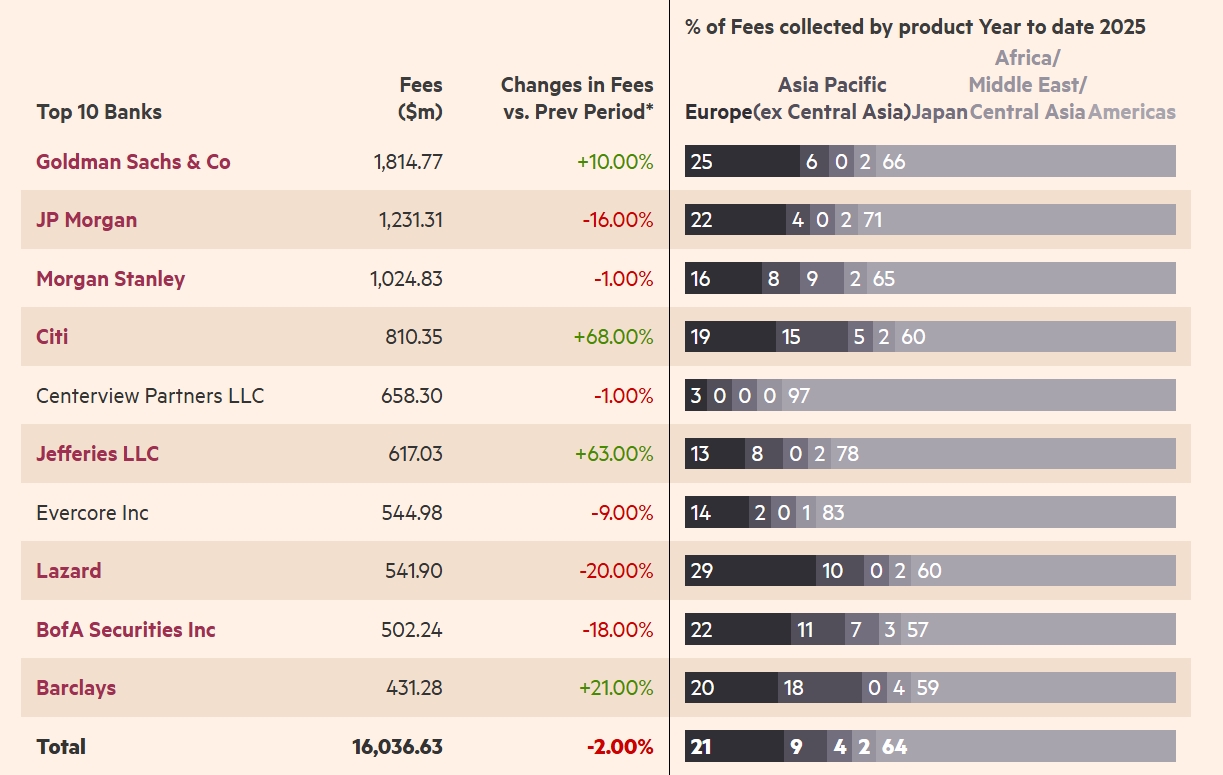
Based off of M&A and looking at the last two quarters, seems like we can see the results.
Thoughts?
Based off of M&A and looking at the last two quarters, seems like we can see the results.
| +134 | Do people still want to go PE? | 39 | 9h |
| +108 | UBS Tech layoff | 48 | 12h |
| +102 | UBS’s M&A BANKERS ARE DOING TERRIBLY. $200M EXTRA IS BEING CUT | 23 | 10m |
| +44 | How do YOU manage networking requests? | 9 | 13h |
| +37 | Lazard hirevue | 11 | 3d |
| +37 | What Differentiates the Best Analysts as AI Improves? | 9 | 2d |
| +35 | Are target prospects getting dumber? | 12 | 11h |
| +33 | MBB Pay Raises | 22 | 6h |
| +32 | Cornell Club T10 Rankings (UPDATED 10/2026) | 19 | 13h |
| +31 | Quitting After First 4 months | 11 | 8h |
Career Resources

Get instant access to lessons taught by experienced private equity pros and bulge bracket investment bankers including financial statement modeling, DCF, M&A, LBO, Comps and Excel Modeling.





Where is UBS?!?!
They Died.
in 2018
JEF on a generational run
Interesting because they're not in the top 10 for deal value per Financial Times, but are #6 in fees. Do middle market deals have higher fee percentages or something?
Usually they do.
A big $10bn deal maybe has 0.5% fee for $50mm fees
A $2bn deal maybe has 1% fee for $20mm fees
A $100mm deal may have 3% fee for $3mm fees
All can vary quite a bit but that’s more of less the idea with rough estimates
Yes - I've worked on (during sellside) $150M deals with 3-4% fees and $1B+ deals with 1% fees.
Anyone know why their stock is down 30% YTD?
taking a very cursory look at it as an incoming fig analyst- all IBs grew after the election in anticipation of more dealflow then dropped after tariffs, with rebounds happening recently.
Jeff doesnt have the other divisions that BBs have to support IB flow or as strong a rx group as some of the public EBs to battle the cyclicality. Feff ballooned in price after election much more than other banks like pjt, evr, laz; with around 30% growth from early nov to peak in dec/jan compared to 10% in other boutiques. Not sure what drove this but im guessing jeff's unique levfin capability was judged as a potential hot market with interest rate cut forecasts which hasn't materialized. Jeff is also selling off their MBD divisions, leaving them even more reliant on ib cycles than previously, so any market volatility will hurt firm earnings even more. while their m&a fees look good above, their equity underwriting fees were cut in half in q2 which is much steeper dropoff than BBs
their current stock price is basically around their stock price from last year, so it could be argued this is more a normalization for them in 1Y stock price than a drop YTD, which was inflated post election more than other banks. their most similar looking comp is moelis which is also flat 1Y. not sure why other banks have rebounded but jeff/moe haven't; but my guess is their reliance on levfin type work for jeff and sponsor backed deals for moelis are not areas the market deems hot currently
Voluptates ad pariatur voluptatem quia atque accusamus amet quia. Mollitia eum quod et officiis autem. Porro consequatur quae blanditiis veniam earum ducimus voluptas.
Architecto similique voluptas nemo incidunt accusamus. Voluptates eveniet veniam ut rerum hic hic voluptatem dolor.
Eius et quis aut veritatis. Perferendis soluta et voluptas mollitia.
Assumenda sunt officiis asperiores tempora aut nemo illo. Modi cupiditate ex fugit vel repellat iste soluta. Nisi autem nisi accusamus neque. Suscipit magnam sunt alias qui ut. Quo laudantium laborum rerum quo id consequuntur id.
See All Comments - 100% Free
WSO depends on everyone being able to pitch in when they know something. Unlock with your email and get bonus: 6 financial modeling lessons free ($199 value)
or Unlock with your social account...