
Qualitative business analysis before valuation - looking for feedback on my structured framework (IB / M&A context)


Hey WSO,
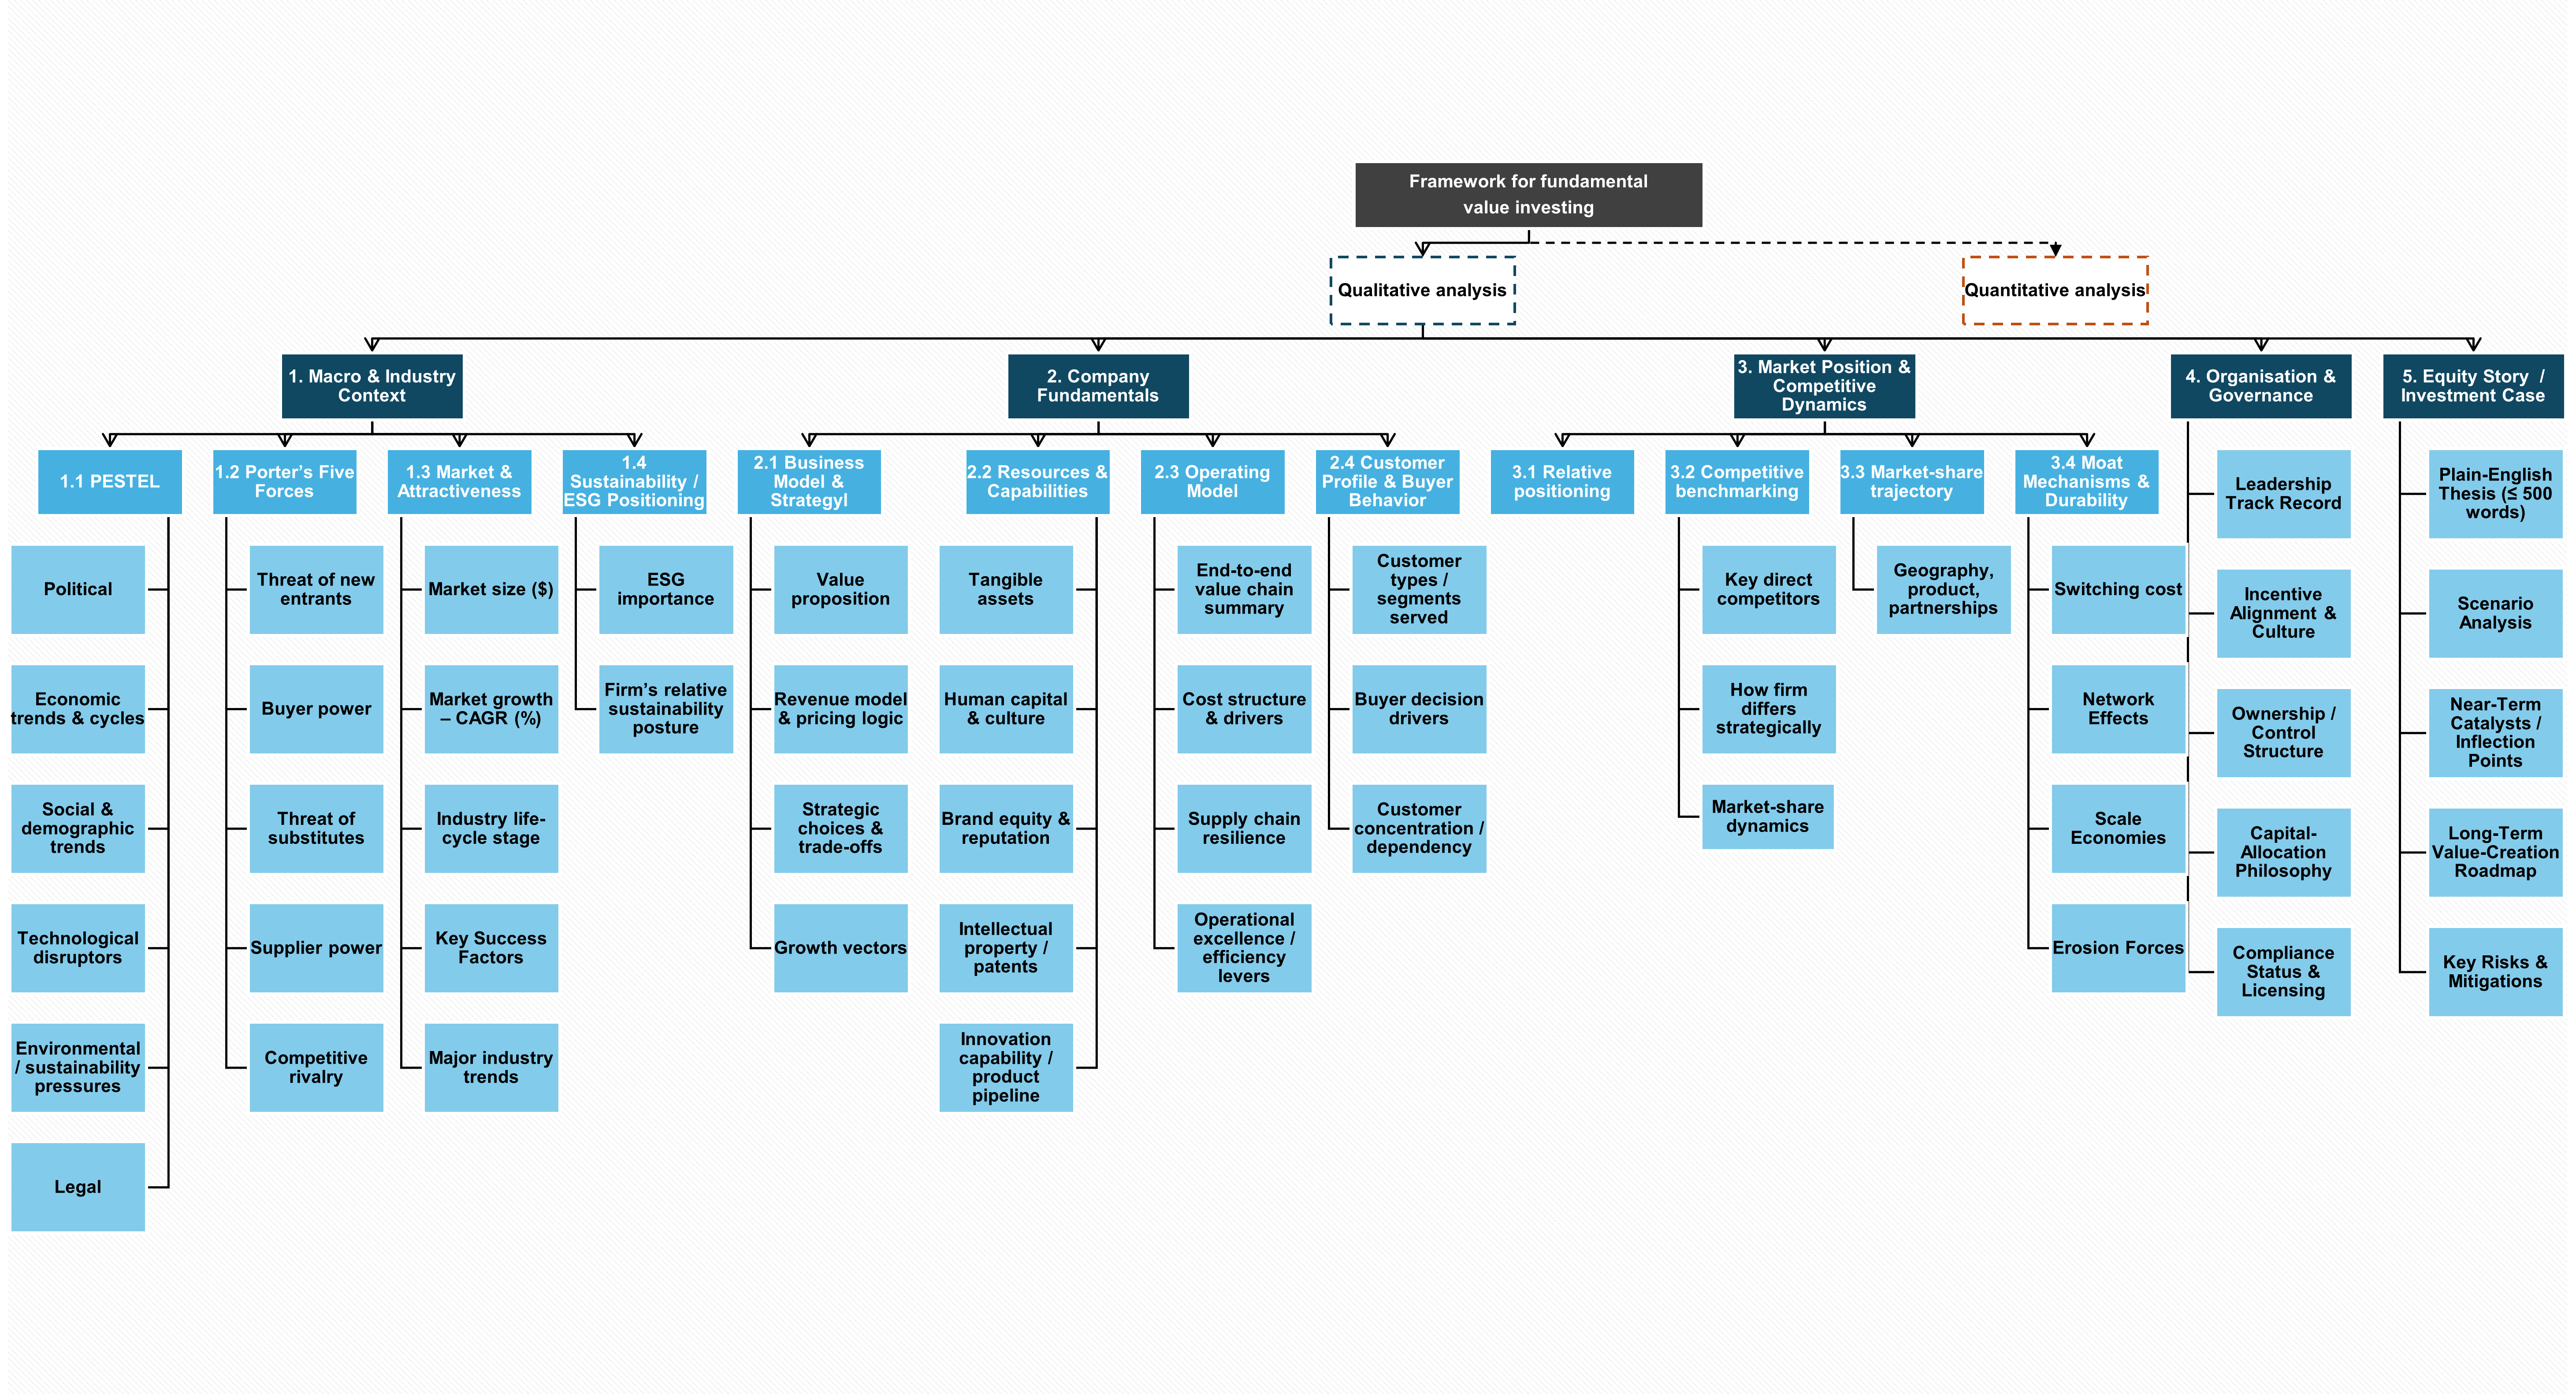
I’m refining a structured framework I use to break down businesses before I build any valuation model (DCF, comps, precedent transactions) or contribute to deal strategy.
I’m a big believer that any model is only as solid as the qualitative foundation behind it — and that understanding a company’s business model, market, and risks is what separates good work from great work.
Why I’m posting
👉 I’d appreciate feedback from the WSO community:
- How do you structure your qualitative business understanding before valuation or advising on deals?
- Are there angles I’m missing that are especially critical in M&A / IB contexts?
- What frameworks or tools have helped you bridge qualitative insights into valuation assumptions?






Iure sed harum adipisci. Aut voluptatum vero rem deserunt atque earum. Voluptatem recusandae reiciendis sit inventore deleniti. Sint necessitatibus voluptas quidem ipsum quam delectus quia. Reprehenderit alias dolores ea sit nihil necessitatibus. Et nesciunt quis vel id.
Consequatur perspiciatis qui optio nobis ut dolore. Veritatis et unde adipisci ea debitis quia est excepturi. Dolore quidem quisquam sed quia error qui. Laborum sed reiciendis quaerat id.
Ut in exercitationem ut sapiente praesentium. Soluta similique dolores quis qui quo sed.
See All Comments - 100% Free
WSO depends on everyone being able to pitch in when they know something. Unlock with your email and get bonus: 6 financial modeling lessons free ($199 value)
or Unlock with your social account...