
UBS Catastrophic Q1-Q3 26, M&A -17%, Outside Top 10 in Americas, EMEA & APAC

It keeps getting worse for the folks at UBs. Market share and performance all declining.
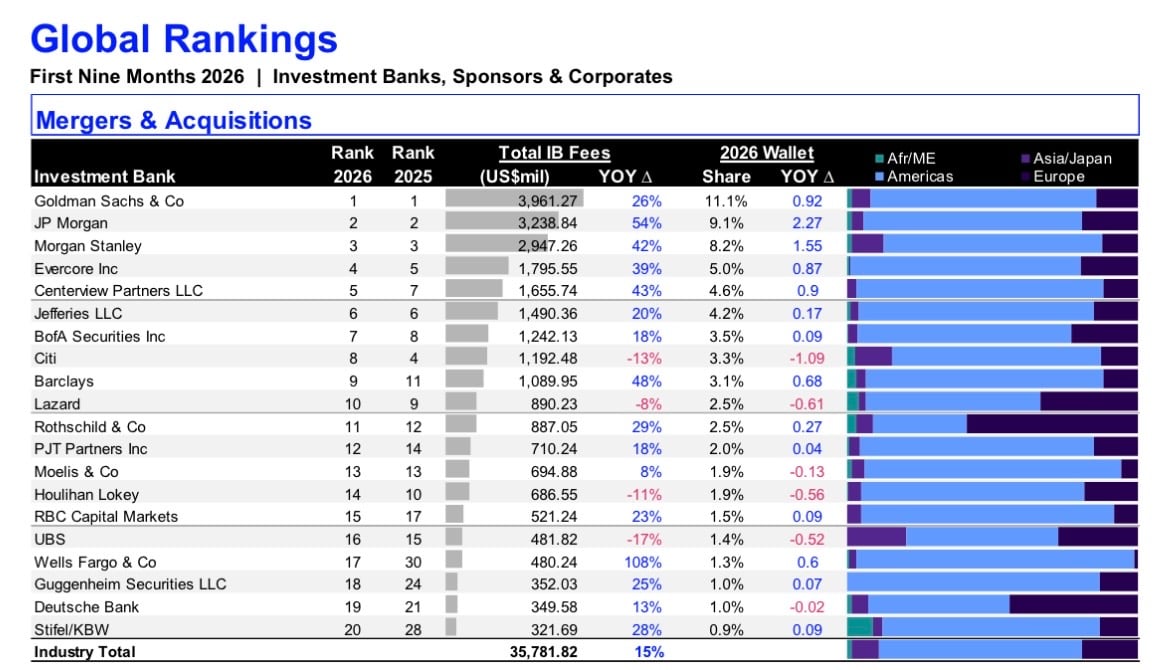
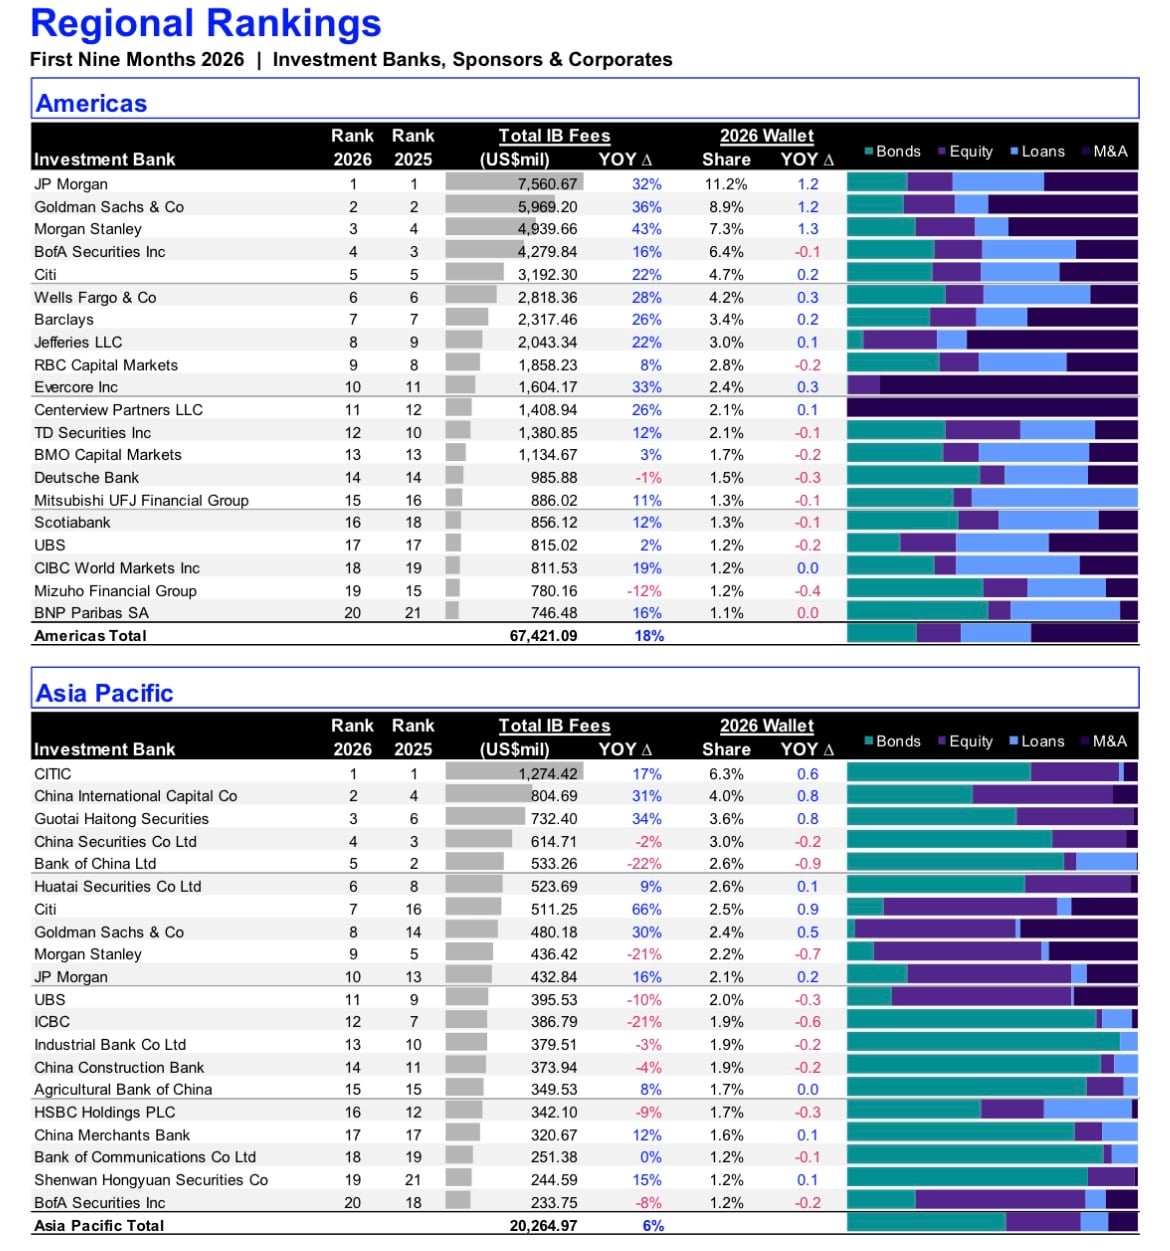
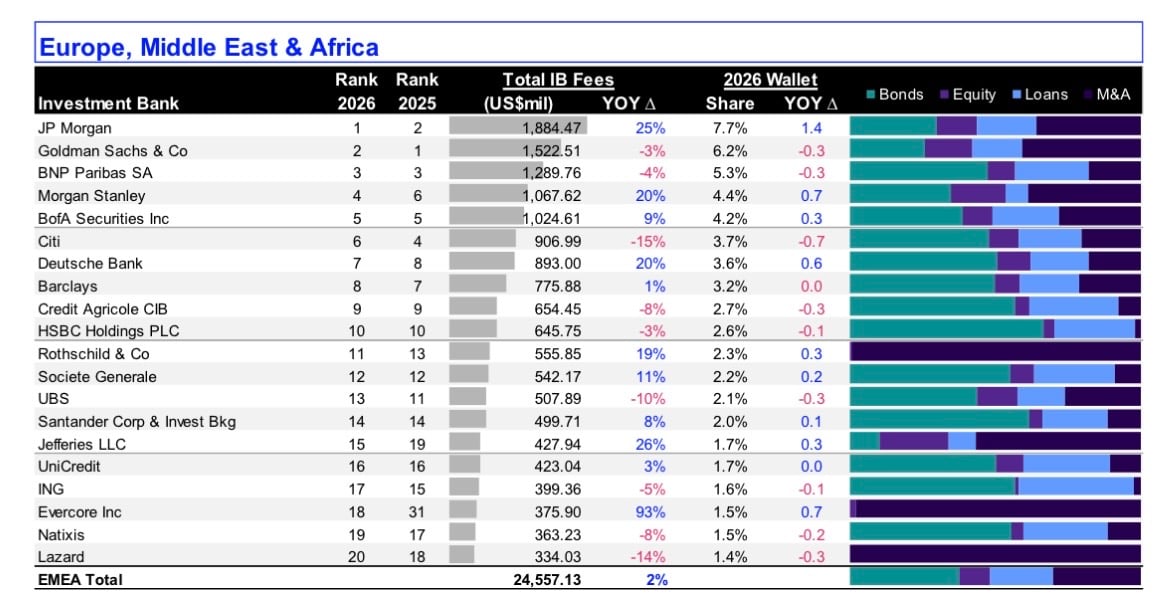
It keeps getting worse for the folks at UBs. Market share and performance all declining.
| +160 | UBS Tech layoff | 52 | 1d |
| +149 | Analyst: Why is UBS IB doing worse than peers?, UBS CFO: No Comment | 24 | 7h |
| +146 | UBS’s M&A BANKERS ARE DOING TERRIBLY. $200M EXTRA IS BEING CUT | 31 | 10h |
| +63 | Leaked Interview Questions to Recruiting Services | 36 | 1h |
| +59 | Are target prospects getting dumber? | 27 | 8h |
| +58 | How do YOU manage networking requests? | 17 | 15h |
| +37 | Quitting After First 4 months | 12 | 1d |
| +34 | MBB Pay Raises | 26 | 1d |
| +19 | Rothschild UK - Mining & Healthcare 2026 | 5 | 3d |
| +19 | Career Crossroads | 2 | 2d |
Career Resources

Get instant access to lessons taught by experienced private equity pros and bulge bracket investment bankers including financial statement modeling, DCF, M&A, LBO, Comps and Excel Modeling.





Terrible leadership, it seems like every year they get worse. But good news they can now blame the Swiss parliament instead of CS integration because the CS integration excuse got old
Funny that they promoted all the people responsible for this decline in the Americas to take on global ownership. Bunch of morons
Americans taking credit for Europe and APAC, instead of actually fixing the Americas franchise
Nothing more American!
Lot of these MDs in the Americas aren’t American…
Americans trying to disassociate from America’s results is the most American thing ever
Congrats on UBS!
Everyone smart at UBS in the Americas hopped ship already
Even the UBS haters don’t hate as much as they used to. It’s an irrelevant platform.
Surprising to see GS #2 in EMEA. Also BNP Paribas is doing extremely well
UBS sucks Cockadoodledoo
League tables keep humbling UBS as they try to go upstream and compete with real BBs head to head
Pretty easy to see Wells is now a BB, UBS is not
Was on the phone with multiple seniors at Wells Fargo who referred to themselves as working at a BB
I can see the US-angle, but Wells outside America is close to non-existent. No way you can call that a BB
No reason why BB has to be global. Give me a 2x the size over global diversification any time
The market continues to consolidate at the top. Those losing market share will end up being swallowed up by one of them
They just hired for their GIG team 2 MDs from Rothschild, 1 from Santander and 1 from JPM. All based in NYC. Is this the revival of UBS??
Heard TMT hired about 20 MDs the last couple years and fell flat on their asses
If you just hire a bunch of unhappy bum MDs who aren’t happy at their current banks (likely because of their own underperformance) they are extremely unlikely to be superstar MDs at a worse platform like UBS
Bearish for GIG bonuses if guarantees and lack of deals squeezing the bonus pool. It’s a zero sum game
If you can’t do well at JPM with all the resources and connections in the world, then you surely won’t do well in a declining market share bussiness that is largely unsure of the value of having an IB
Results so bad Sergio started hinting as such in recent interviews
I don’t think the IB survives years of high interest rates, they’ll get bought out or dissolved. Can’t just burn cash in a high interest rate environment
MV has to take the fall for this right? If he doesn’t it shows either UBS isn’t a serious organization or Sergio simply loves Marco
Both of those statements are completely accurate
Interesting. Dealogic shows UBS at #8 globally by M&A YTD. Generally curious to see how the methodology at LSEG differs as would have thought it should show a similar picture.
UBS iS GrEaT TrUtHeR oVeR hErE
I’m sure UBS is just misunderstood by the league tables.
LSEG more accurate since its fee based.
Dealogic valuing 0/No fee work based on EV.
Two sides to the coin though - fees aren’t recognized until deals actually get completed (rather than EV which gets recognized when deal is announced) therefore solely looking at fees is a lagging indicator.
I prefer looking at both EV and fees and basing overall rankings as a mix of both (same way you would look at a football field for valuation rather than just comps or just the DCF).
All in all - LSEG or Factset transaction value rankings are my go-to, can also separate by region/product.
UBS is a whore for no fee / no work deal credit.
If you can’t work real deals, beg for no fee deal credit.
I think it’s time to remove UBS as BB and put WF in its space instead, the gap between the two is widening every quarter
UBS will be top 5 in the americas by the end of 2026.
-Marco, 2023
The three year (24-26)plan has been a total failure
UBS can still get there so long as they are able to lead the upcoming 4 party merger between Open Ai, Anthropic, SpaceX, Google
I see great synergy between Nvidia and Aramco - gonna pitch that instead
Will say revenue for M&A is typically delayed and contingent on deals closing, so this is based on 2025 deal flow. Not following how UBS has done since then, but 2027 advisory revenues will be more reflective of 2026.
There’s a new excuse that doesn’t involve Credit Suisse or Swiss capital requirements.
UBS juniors regret to inform you UBS revenue and deal flow is currently in a rain delay.
wtf is all this ubs hate? its like one dude?
lot of disgruntled ex analysts/asos
Cupiditate consectetur officiis beatae laborum quisquam illum sit. Error dolor ratione et in beatae officia cum ab. Aut modi atque ipsam quaerat. Amet molestiae dolores occaecati aut et molestiae nobis nobis.
Aut ullam odit qui omnis reiciendis. Aut aliquid qui quos. Impedit eos magnam et dignissimos est. Et placeat et iusto assumenda sit veniam et. Placeat voluptate eos blanditiis. Ut vel atque omnis labore. Rerum soluta eos deleniti officia consequuntur at et est.
Quam enim harum iusto autem numquam quidem. Maxime non quas expedita et quo.
Qui qui doloremque est saepe sit quae commodi sequi. Voluptatibus dolorum sed voluptas qui qui corporis. Aut quo laboriosam at id dicta. Commodi culpa aut omnis officia ut beatae. Nemo qui totam tempora.
See All Comments - 100% Free
WSO depends on everyone being able to pitch in when they know something. Unlock with your email and get bonus: 6 financial modeling lessons free ($199 value)
or Unlock with your social account...
Quam vel dicta reiciendis quam quasi consequatur aspernatur in. Maxime quasi et quam eaque odit. Qui debitis nostrum et doloribus sunt et. Natus consequatur id id esse corporis aut inventore.
Incidunt odit tempora perferendis itaque expedita consequuntur. Repellendus placeat iste officiis. Numquam deleniti ratione veniam deleniti aliquid qui sunt. Nihil quasi voluptas occaecati sequi. Aperiam deserunt quis eum facilis ipsum consequatur et.
Laboriosam magni voluptates doloribus consequuntur. Doloribus aut est et qui. Modi tempore cumque et provident magni consequatur quo. Eius culpa non ea possimus dolorum nemo aliquid. Ratione error iste dignissimos occaecati.